There is a paradox at the heart of Australian small business banking. The more carefully an owner structures their affairs, the less bankable they look. Income drawn efficiently through companies and trusts reads as thin serviceability. Capital reinvested into property and plant reads as low liquidity. An owner can be wealthy, profitable and creditworthy in every practical sense and still fail the template.
The pool of people exposed to that paradox is large and growing. Australia had 2,814,778 actively trading businesses at June 30, the Australian Bureau of Statistics reported, and companies posted the largest net growth of any legal structure, rising 5.2% to 1,271,197. Over the past decade, bank lending systems were recalibrated around salaried-employee serviceability, built on predictable payslips and income presented in exactly the format a scorecard expects. The recalibration made the system safer. It also made it blind to a certain kind of borrower, and the money has started to go elsewhere. Credit from non-banks has been growing faster than bank credit, the Reserve Bank of Australia said in its March Financial Stability Review.
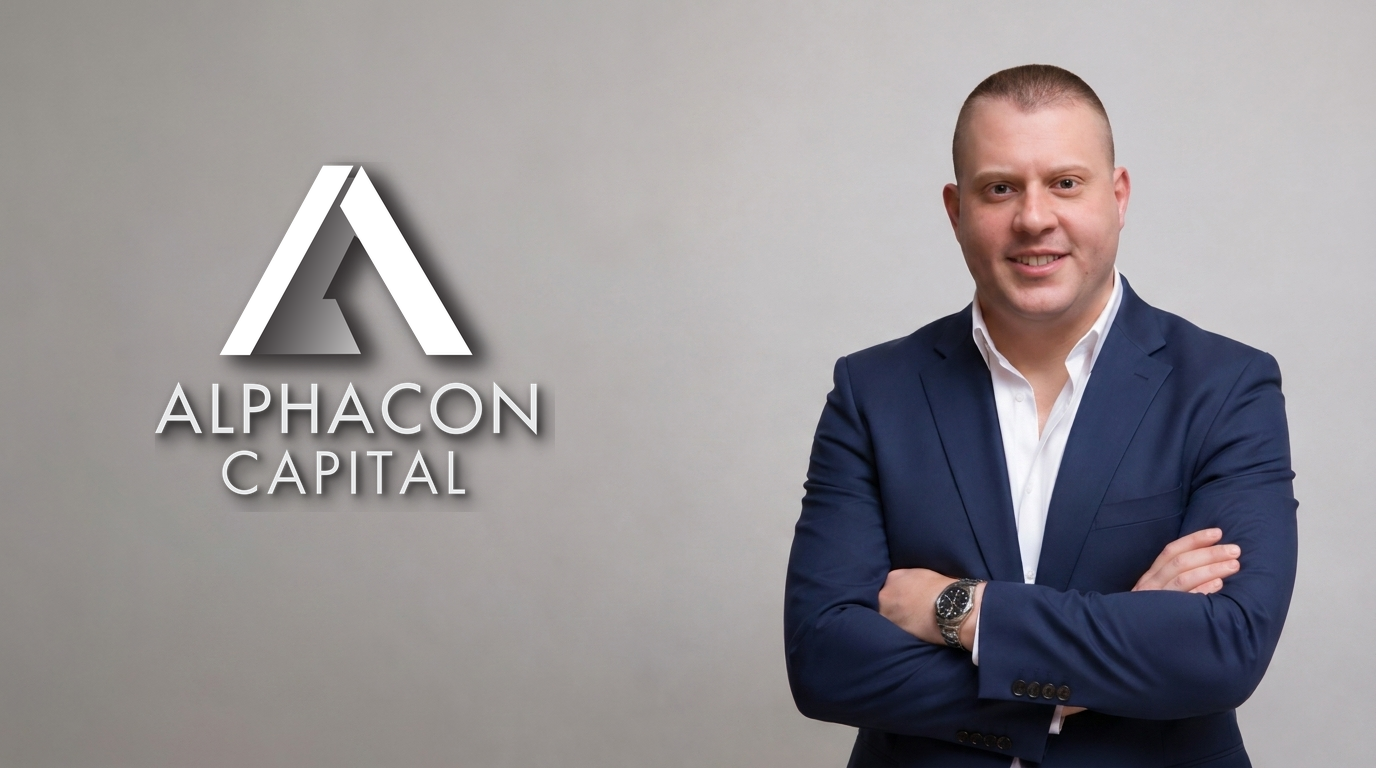
“The banks are not being malicious. They are being systematic,” says Hadley Shapiro, founder and chief executive of Sydney private lender Alphacon Capital. “But systematic means the template decides, and the template was not built for business owners. So good operators get a no that has nothing to do with their actual risk.”
The scorecard sees the salary, not the business
Consider the mechanics. A 20-year operator draws a modest salary on their accountant’s advice, leaving profit in the trading company or distributing it through a family trust. The business is strong and the balance sheet is real, yet the bank’s serviceability engine sees only the salary. The computer does not decline the business for being risky. It declines it for being structured like a business instead of an employee.
For years, a rejection from the majors pushed those businesses toward the unruly end of the private market, where pricing was opaque and the exit was an afterthought. Opaque default terms and fees that surfaced at settlement are the stories that have kept parts of the sector’s reputation in the shadows.
“There is a generation of good operators the banks can no longer serve and the cowboys should never touch. That gap is the whole business,” Shapiro says.
Alphacon’s answer is deliberately boring, and Shapiro regards that as the point. The firm writes business-purpose loans to companies and corporate trustees, secured against real property. Pricing is disclosed before a borrower commits. The exit is agreed before settlement, typically a refinance to a mainstream lender once the borrower’s position is presented properly, or a sale that was always part of the plan. Indicative terms come within 24 hours because the assessment rests on two questions: what is the asset worth, and how does this loan end?
“Every loan we write has to have a clean way out before it has a way in. If the exit is not obvious, the answer is no. That is what separates lending from hoping.”
Brokers are the quality filter
The businesses crossing the gap tend to look alike. A wholesaler with a paid-down commercial unit funds a season of stock and repays it before a bank would have finished processing the application. A family company refinances a commercial property out of a maturing facility while it finalizes the sale that clears everything. A services business borrows against its premises to fund an acquisition its bank backed in principle but could not settle in time. Each is a business in motion, borrowing against real security, with a defined end date.
Finance brokers sit at the junction. One who knows both worlds can place a client with a major bank when the file fits and reach for disciplined private capital when it does not, without the client ever drifting toward the cowboys. Shapiro sees the channel as a filter as much as a pipeline.
“A good broker has seen every lender behave at their worst. Where they keep sending files tells you who has kept their promises.”
The private market has blind spots of its own
The case for private lenders filling the gap is strong. The evidence that all of them will fill it well is thinner. A report commissioned by the Australian Securities and Investments Commission and published in September 2025 sized Australian private credit at about A$200 billion, roughly half of it tied to real estate, and found that basic terms such as “loan to value ratio” and “senior debt” were used inconsistently enough to confuse investors. The RBA’s March review reported, from its liaison with lenders, some easing in non-bank lending standards, which it judged modest so far. Competition for the borrowers banks turn away is exactly the condition under which standards slip. And with Cotality reporting national dwelling values down 5.2% from their March peak, property across the market is worth less than it was six months ago. A business a bank declined for structural reasons and one it declined for good reasons can look identical in a hurried submission.
That distinction is the one Alphacon has to keep drawing, file by file. The template made Australia’s banks safer and, for a large class of business owners, blind. Shapiro’s wager is that a lender can see what the template misses without forgetting why the template was built.